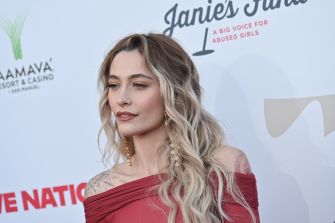
Paris Jackson is challenging more than $109 million in compensation tied to Michael Jackson’s estate, accusing longtime executor John Branca of “persistent incompetence” and asking a judge to cut the management rate paid on the late singer’s entertainment income.
In a motion filed Oct. 23, 2026, Jackson argues that Branca failed to provide complete financial accountings for 2023 and 2024 despite seeking approval for $109,219,648 in combined compensation involving the estate’s co-executors and the Ziffren law firm.
Her attorneys called the amount “particularly offensive” in light of what they describe as years of delayed or incomplete financial reporting.
According to the filing, Branca set a Sept. 15 deadline to submit the outstanding accountings but failed to provide records Jackson considers complete and accurate. Her lawyers characterized portions of the filings as incomplete and described the 2024 submission as little more than a placeholder.
“It is unclear how executor could calculate and distribute such an amount with any confidence and yet be unable to file complete and accurate accountings years later,” the motion states.
Jackson is asking retired judge Mitchell Beckloff to reduce the compensation rate from 15% to 10% of the estate’s gross entertainment-related income for 2023 and 2024 and keep the lower rate in place until complete accountings through 2026 are filed.
The requested reduction would affect Branca’s compensation going forward while tying restoration of the higher percentage to the financial disclosures Jackson says remain outstanding.
The Michael Jackson estate has strongly rejected her allegations.
A spokesperson for the Branca-led estate called the motion “completely without merit” and disputed Jackson’s characterization of the payments as executor compensation. The estate maintains that Branca and the late co-executor John McClain waived traditional executor fees when they took control of the estate and instead receive a separate, court-approved management fee for operating Michael Jackson’s business interests.
The estate also says the 2023 and 2024 accountings have been filed, putting the two sides at odds over whether those records satisfy the court’s reporting requirements.
Branca has managed Michael Jackson’s business affairs since the singer’s death in 2009. Estate attorneys have credited his leadership with transforming an operation burdened by more than $500 million in debt into an entertainment business valued in the billions.
Jackson’s latest challenge follows a separate legal win earlier this year over $625,000 in bonuses paid to outside attorneys working for the estate.
In an April 29 ruling, Beckloff found that the estate had not provided enough information to establish that the bonuses were just and reasonable. He said the amounts appeared arbitrary based on the evidence presented and ordered the money returned to the estate.
The ruling also placed additional restrictions on future bonus payments to attorneys without beneficiary consent or court approval.
That earlier dispute grew out of Jackson’s broader push for greater financial disclosure from those managing her father’s estate. Her latest motion now targets the much larger compensation connected to the estate’s entertainment income.
Michael Jackson died June 25, 2009, at age 50 from an overdose of the anesthetic propofol. His estate has since grown into one of the entertainment industry’s most valuable, generating revenue through his music catalog, licensing deals, and other business interests.
Paris Jackson, 28, is a beneficiary of the estate along with her brothers Prince and Bigi.
Her attorneys argue that the size of the compensation makes timely and accurate financial reporting especially important, while the estate maintains that its management has generated substantial wealth for Michael Jackson’s beneficiaries and that the latest challenge mischaracterizes how its managers are paid.
Beckloff is scheduled to hear Jackson’s request on Dec. 4, when the court is expected to consider whether the compensation rate should be reduced and whether the estate’s financial disclosures satisfy its reporting obligations.